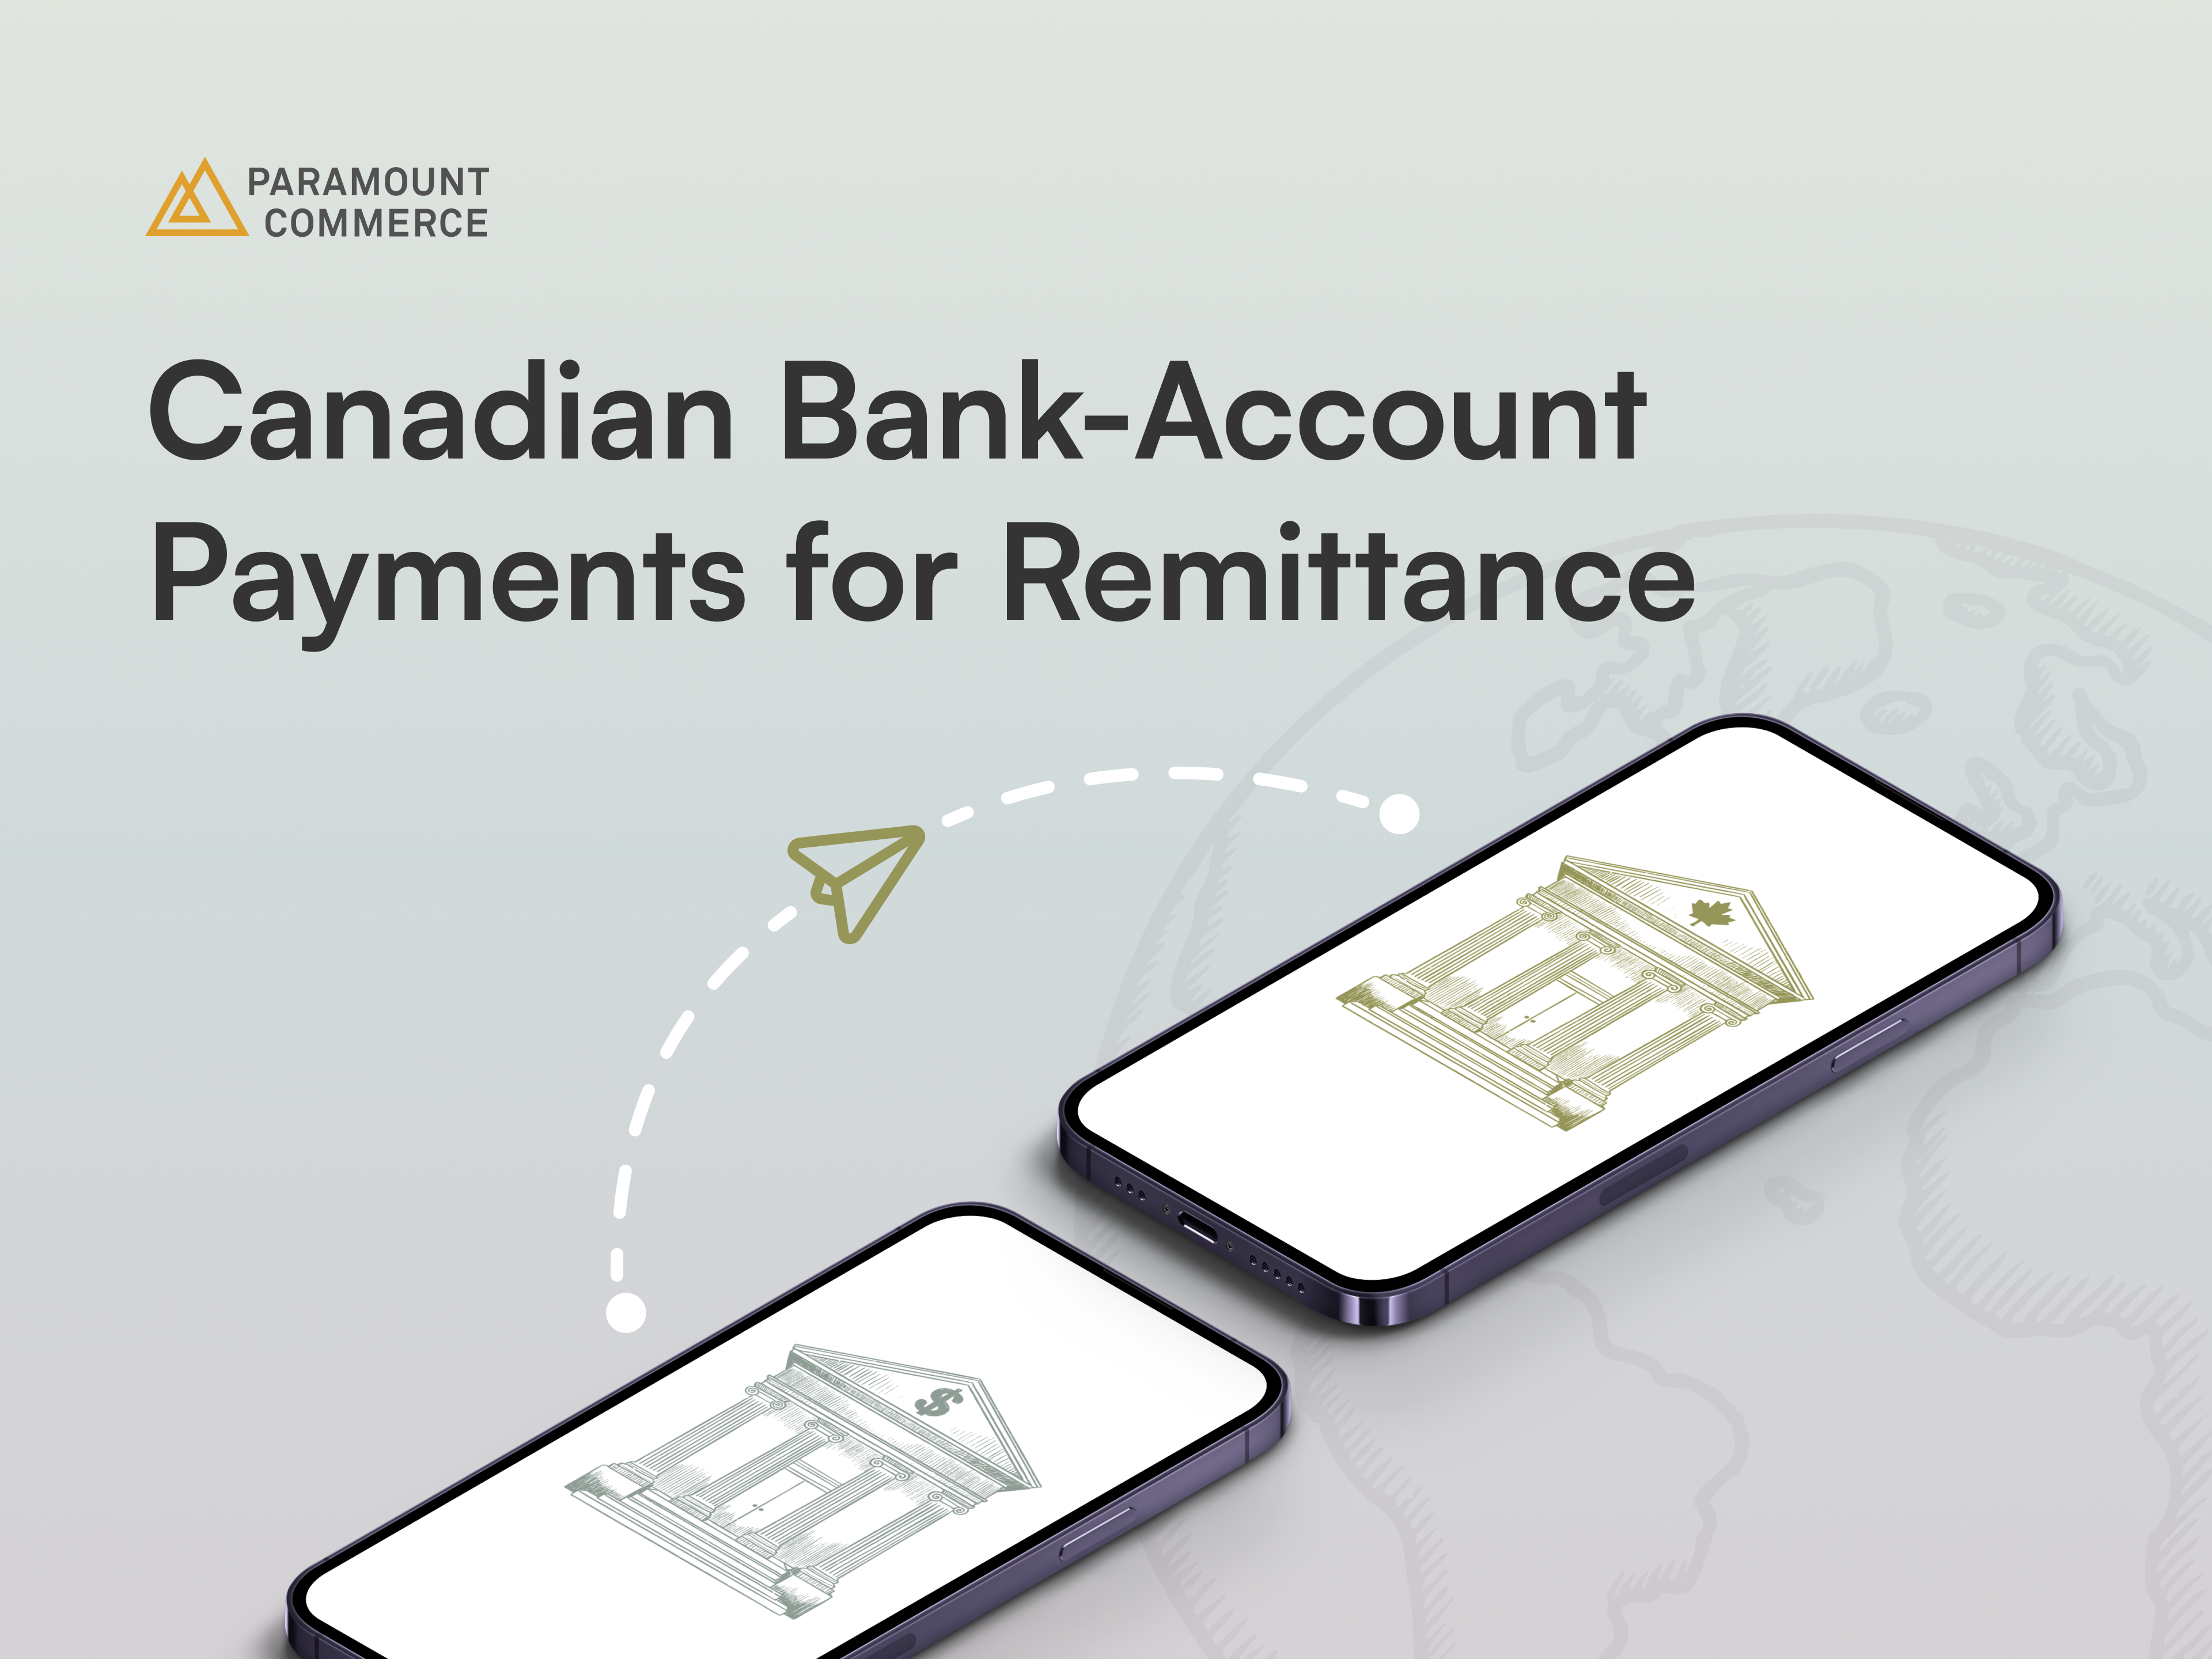
Canadian remittance businesses need payment options that make it easy for senders to fund transfers while giving operations teams the visibility and controls required to move money safely through the broader remittance process.
Bank-account payment methods can play an important role in that experience. For Canadian customers, an Interac e-Transfer®-based pay by bank option can offer an alternative to card funding and provide a familiar, bank-authenticated way to pay for a transfer.
Understanding those differences is essential before adding a new payment method.
A remittance transaction involves multiple stages. The payment method a sender uses to fund a transfer is one stage; delivering money to the recipient is another.
For Canadian remittance businesses, pay by bank commonly supports the sender-funding stage. A customer approves a payment from an eligible bank account. This gives the remittance platform a bank option, rather than a card-only checkout. Some payment providers may also support eligible local Canadian payout flows.
A bank-based pay-in allows a sender to fund a remittance transfer directly from their bank account.
A typical flow may look like this:
For a Canadian audience, Interac-based pay by bank can be a useful option because it aligns with a payment experience many customers already recognize. It may help a business offer a more localized funding journey while reducing dependence on card-only payments.
Bank-account payment methods can be especially relevant when a remittance business:
Pay by bank does not need to replace every other method. Many businesses benefit from offering more than one funding option, then using payment placement, customer messaging, and performance data to guide users toward the most appropriate method.
A common question from remittance companies is whether an Interac pay by bank solution reaches every Canadian bank account.
The practical answer is that availability should be confirmed for the specific payment flow. It can depend on several factors:
This is why “bank coverage” should not be treated as a simple yes-or-no feature. A provider should be able to explain the expected user journey, applicable eligibility conditions, relevant limits, known exceptions, and how unsupported scenarios are handled.
Pay by bank solutions such as Interac can help reduce a business’s reliance on card-funded transfers and may reduce exposure to some card-specific chargeback and dispute patterns.
With a bank-authenticated payment flow, the customer authorizes payment from their bank account rather than entering card details. For a remittance business, that can create a different payment experience and risk profile than a card-only model.
A Canadian pay by bank provider can support the local payment leg of a remittance journey. It may help a business collect funds from Canadian senders and, where supported, facilitate eligible local payouts.
It does not automatically provide every capability required to operate a remittance service.
A complete cross-border remittance operation may also require:
A practical approach is to select specialized partners for the parts of the stack where they add the most value. A Canadian bank-based payments provider can support a localized sender-funding experience, while the remittance business’s core platform or partner ecosystem manages the broader transfer lifecycle.
Before adding a Canadian pay by bank option, a remittance business should ask:
For remittance businesses serving Canadian customers, Paramount Commerce can support Interac-based and pay by bank payment experiences for eligible Canadian funding flows.
This can give businesses a local alternative to card-only payment and a bank-authenticated customer journey for sender funding. Depending on the approved product configuration and eligibility requirements, Paramount Commerce also supports relevant local Canadian payment flows.
The remittance business continues to manage, or work with partners that manage, FX, customer verification, compliance, cross-border settlement, corridor operations, and delivery to the recipient.
Assess whether a Canadian bank-based payment flow fits your remittance business. Speak with Paramount Commerce about your funding requirements, payment volumes, and implementation needs: https://www.paramountcommerce.com/book-a-demo
1) Top Payment Providers for Canadian Remittance Businesses
2) What Remittance Companies Need to Know About Pay by Bank
3) How pay by bank is improving Canadian remittance payments
What is the difference between remittance pay-ins and payouts?
A pay-in is the sender funding a transfer, such as paying from a Canadian bank account or card. A payout is the delivery of money to the recipient through an eligible bank account, mobile wallet, cash-pickup location, or another receiving method. They are separate parts of the remittance journey.
Can Canadian customers fund remittances from a bank account?
Yes, depending on the payment provider, customer eligibility, financial institution, account type, transaction amount, and supported payment flow. An Interac-based pay-by-bank option can provide an alternative to card funding for eligible Canadian customers.
Does pay by bank work with every Canadian financial institution?
Availability can vary by participating financial institution, account eligibility, product configuration, payment type, and applicable controls. Remittance businesses should confirm the expected bank coverage and exceptions for their specific use case rather than assume every account is eligible.
What affects payment limits for Canadian bank-account remittance funding?
Limits can depend on the sender’s financial institution, account type, transaction value, payment flow, provider configuration, and risk controls. Businesses should confirm applicable customer and operational limits before designing a remittance payment journey.
Can pay by bank reduce card chargeback exposure?
Pay by bank can reduce reliance on card-funded payments and may reduce some card-specific chargeback and dispute patterns. It does not eliminate fraud or payment risk, so remittance businesses still need strong KYC, AML, monitoring, customer support, and exception management processes.
Does a Canadian pay by bank provider replace FX and international payout partners?
No. A Canadian pay by bank provider supports the payment leg, such as sender funding and, where available, eligible local payment flows. A cross-border remittance business still needs FX, compliance, settlement, corridor partners, and recipient-delivery infrastructure.
What should a remittance business ask before adding pay by bank?
Ask about supported pay-in and payout flows, Canadian bank coverage, eligibility, transaction limits, payment confirmation, fraud controls, reporting, integration options, exception handling, and compatibility with your FX, KYC, AML, and corridor partners.
Fintech trends and insights,
explained in 5 minutes or less
Fintech trends and insights,
explained in 5 minutes or less